
What if the smartest way to build a core portfolio is not trying to pick winners?
For most investors, index funds perform better as the long‑term anchor.
They give broad diversification, tiny fees, and steady market returns that don’t erode over time.
Active funds can beat benchmarks sometimes, but higher fees, tax drag, and manager turnover often wipe out that edge.
We’ll show when active choices might earn a small spot at the edges, and why index funds should be the default for your core.
Core Portfolio Comparison: How Index Funds vs Active Funds Perform as Long‑Term Anchors
For a core portfolio, index funds usually deliver more consistent results with less drag over decades. Active funds can outperform in specific windows or market pockets, but the gap between gross and net returns widens each year as higher fees compound against you.
Over the 10‑year period ended March 31, 2026, about 79% of active stock fund managers beat their prospectus benchmark, and roughly 83% of active bond managers did too. Those numbers look good for active funds. But they only include funds with a full 10‑year track record, which means underperformers that closed or merged away aren’t in the data. When you widen the lens to all active funds launched during that window, historical studies across many time frames show that 60% to 90% of active managers trail their benchmark over 5 to 15 years, especially after fees and taxes.
The cost difference compounds quietly but hard. A broad market index fund charging 0.08% annually turned $100,000 into roughly $746,000 over 30 years at a 7% gross return. An active fund charging 0.80% yielded about $609,000. That’s a $137,000 gap caused by fees alone. Add higher turnover and more frequent capital gains distributions, and the after tax difference gets even wider.
Comparison summary for core allocations:
- Cost: Index funds charge 0.03% to 0.25%. Active funds run 0.50% to 2.00%.
- Consistency: Index funds track the benchmark reliably. Active performance varies widely and often doesn’t persist.
- Tax implications: Index turnover stays 2% to 20%. Active turnover hits 40% to 150% or more, triggering more taxable gains.
- Manager risk: Index funds eliminate it. Active funds introduce it as a central variable.
- Monitoring time: Index funds need annual rebalancing. Active funds require ongoing due diligence on holdings, strategy drift, and manager tenure.
For the bulk of a core allocation (the 60% to 90% of your portfolio anchoring long term wealth), index funds offer the clearest path to predictable, low drag market returns.
Defining a Core Portfolio and How Index vs Active Funds Fit Into It
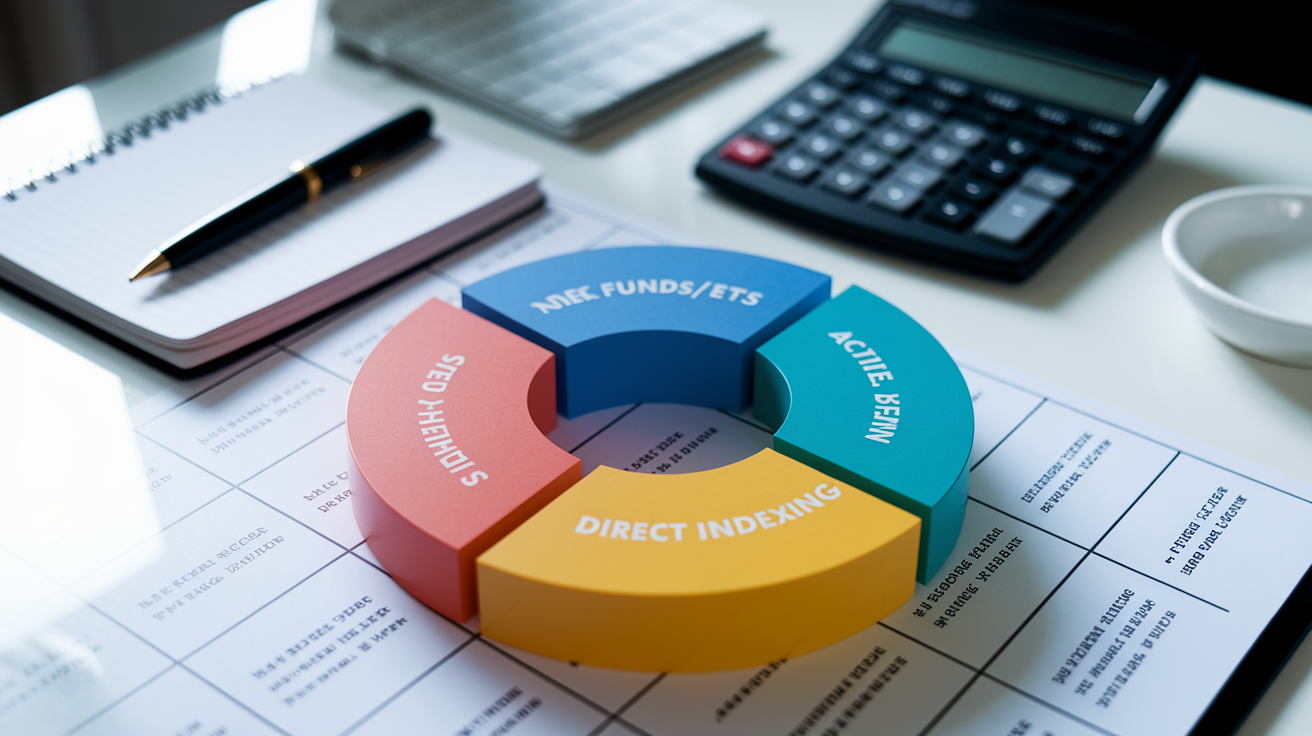
A core portfolio is the largest, longest duration piece of your investable assets. Usually 60% to 90% of the total. It’s built to capture broad market returns over 10 to 30 years or more, with minimal cost and minimal need for hands on management. The goal is steady growth you can count on, not excitement.
Index funds align naturally with that mission. They give you instant diversification across hundreds or thousands of stocks or bonds, deliver predictable market beta, and keep expenses and turnover low. Active funds introduce concentrated bets, higher fees, and the risk that a manager underperforms or leaves. That doesn’t mean active funds never belong in a core allocation, but they need more evidence, more oversight, and a narrower slice of your portfolio.
| Fund Type | Fit for Core | Primary Advantages | Primary Drawbacks |
|---|---|---|---|
| Index funds / ETFs | Strong (default for 70% to 90% of core) | Low cost, broad diversification, predictable tracking, tax efficient | Won’t beat the benchmark, limited flexibility |
| Active mutual funds | Moderate (satellite or selective core use) | Potential to outperform, flexibility, targeted strategies | Higher fees, manager risk, tax drag, inconsistent results |
| Direct indexing | Moderate (suitable for large taxable accounts) | Tax loss harvesting, customization, real time transparency | Higher minimums, more complexity, tracking error if over customized |
| Hybrid / blend | Strong (combines cost control with targeted alpha) | Balanced exposure, diversified manager risk | Requires allocation discipline and periodic review |
Most investors anchor the core with passive index funds because they deliver diversification, low cost, and minimal tax friction by default. Active funds get evaluated more carefully, assigned to smaller sleeves where manager skill, niche exposure, or specialized strategies justify the higher fees and closer watch. The core stays simple. The edges get selective.
Passive Index Strategy Fundamentals for Building a Core Allocation
Index funds work by replicating a market benchmark. Either buying all the securities in the index or holding a statistically representative sample. A total U.S. stock market index fund might own 3,500 stocks. An S&P 500 fund buys all 500 large cap names. Either way, the fund’s performance should stay very close to the index itself.
The difference between the fund’s return and the index’s return is called tracking difference, and it’s usually small. A few basis points annually. Tracking error measures how much that difference bounces around over time. Broad market index funds keep both low because they trade rarely, hold diversified positions, and don’t bet on individual stock picks. That consistency is exactly what a core allocation needs.
Four key strengths of passive funds for a core holding:
- Low cost. Annual expense ratios of 0.03% to 0.25% mean fees take a tiny bite out of returns each year.
- Broad diversification. Owning the whole market or a large segment spreads risk across hundreds or thousands of companies.
- Consistency. You get the market return, minus a predictable fee. No manager bets. No surprise underperformance.
- Tax efficiency. Turnover of 2% to 20% annually keeps realized capital gains low, especially in ETF structures that use in kind redemptions.
ETFs add another tax advantage. When large institutions redeem shares, the fund can deliver low cost basis securities in kind instead of selling them and triggering a taxable gain. Those redemptions happen in creation units worth millions of dollars, so individual investors can’t use the mechanism directly. But everyone in the ETF benefits from fewer capital gains distributions. For a core holding you plan to own for decades, that structural advantage compounds into real after tax savings.
Active Management Fundamentals and When Active Funds May Justify Core Allocation
Active funds employ portfolio managers who hand pick securities and trade more frequently, aiming to beat a benchmark or hit a specific goal like income, capital preservation, or exposure to a niche sector. Instead of mirroring the S&P 500, an active large cap fund might hold 30 to 80 stocks the manager believes will beat the index.
That flexibility creates opportunity. But it also introduces manager risk. The portfolio’s success depends on whether the manager’s calls are correct, whether the strategy stays disciplined, and whether key personnel stick around. Performance can swing more widely than a passive fund, and many active managers trail their benchmark over long periods once fees and taxes are factored in.
Higher turnover is standard. While an index fund might turn over 5% of its holdings in a year, active funds often trade 40% to 150% or more. Every sale of a profitable position triggers a capital gain, and those gains flow to shareholders as taxable distributions. That’s why active funds usually fit better inside tax advantaged accounts like IRAs, where you defer or avoid the tax hit.
When active funds can add value to a core allocation:
- Inefficient markets. Small cap, micro cap, and certain emerging market segments where information advantages and skilled research can uncover mispriced securities.
- Specialized fixed income. Municipal bonds, high yield debt, or floating rate strategies where active management of credit risk and duration can generate alpha.
- Conviction in a skilled manager. Access to a manager with a long, consistent track record and a scalable, repeatable process.
- Event driven or arbitrage strategies. Situations where specific expertise (merger arbitrage, distressed debt) offers return sources uncorrelated with broad equity markets.
- Smaller, targeted satellite positions. Using 10% to 30% of the portfolio for active bets while keeping the core passive reduces overall manager risk and cost drag.
Even in those scenarios, the expected net alpha (after fees and taxes) should top at least 1% annually to justify the higher cost and complexity. If you can’t explain why a specific active manager is likely to beat the benchmark, default to the index fund.
Historical Evidence Comparing Index vs Active Results Over Long Horizons
For the 10 year period ended March 31, 2026, roughly 79% of active stock fund managers beat their prospectus benchmark, and about 83% of active bond fund managers did too. That data includes only funds with a minimum 10 year track record, which means funds that closed, merged, or disappeared aren’t counted. Survivorship bias can make the active category look stronger than it really is.
Broader academic studies and industry reports covering all funds (including those that didn’t survive) tell a different story. Across many time windows, 60% to 90% of active managers trail their benchmark over 5 to 15 years, with the underperformance rate often landing near 70% to 80% for large cap equity funds over a decade. The gap widens as the time horizon stretches, because fees and turnover compound against the fund every single year.
Reconciling Conflicting Performance Data
Different studies arrive at different numbers because they use different methods. Some include only funds still operating at the end of the measurement period. Others start the clock when a fund launches, capturing closures and mergers. Some compare funds to their stated prospectus benchmark. Others use broader style box indexes. And some report gross returns before taxes, while after tax comparisons favor index funds even more strongly.
Three methodological factors that shape the results:
- Survivorship bias. Excluding failed or merged funds inflates the performance of the “average” active fund that remains.
- Benchmark selection. A fund’s prospectus benchmark might be easier to beat than a broad market index. Style drift can complicate the comparison.
- Time period and market conditions. Active managers tend to outperform more often in volatile, declining, or range bound markets and underperform in long, steady bull runs.
For a core portfolio, the safest assumption is that most active managers won’t consistently beat a low cost index fund after fees and taxes over 10 to 30 years. A small minority will. But identifying them in advance is hard, and past outperformance doesn’t predict future results reliably.
Costs, Expense Ratios, and How Fee Drag Compounds Over Decades
Index funds typically charge annual expense ratios between 0.03% and 0.25%. Broad market index ETFs often sit at the low end (0.03% to 0.10%), while niche index funds (sector, international small cap) can reach 0.20% to 0.25%. Active mutual funds run 0.50% to 1.20% for large cap strategies and can hit 1.00% to 2.00% for specialty, small cap, or actively managed bond funds.
That spread looks small in any single year. But compounded over 30 years, the difference reshapes your ending balance. Assume a gross market return of 7% annually and an initial investment of $100,000. An index fund charging 0.08% delivers a net return of 6.92% and grows to about $746,000. An active fund charging 0.80% nets 6.20% and ends at roughly $609,000. The $137,000 gap comes entirely from fees.
| Fee Level | Net Annual Return (7% gross) | 30‑Year Value ($100k start) | Difference vs 0.08% Fee |
|---|---|---|---|
| 0.08% | 6.92% | ≈$746,000 | — |
| 0.50% | 6.50% | ≈$647,000 | −$99,000 |
| 0.80% | 6.20% | ≈$609,000 | −$137,000 |
| 1.20% | 5.80% | ≈$559,000 | −$187,000 |
Every basis point matters when you’re building wealth over multiple decades. Low cost index funds dominate cost adjusted comparisons because they give you more of the market’s return and keep more of your money working instead of paying fees. For a core allocation, choosing funds with expense ratios at or below 0.20% is one of the simplest, highest impact decisions you can make.
Tax Efficiency, Turnover, and Placement: Index vs Active for Taxable and Retirement Accounts
Index funds turn over 2% to 20% of their holdings each year. Active funds trade far more, often 40% to 150% or higher. Every time a fund sells a profitable position, it realizes a capital gain. If the fund is held in a taxable brokerage account, that gain gets distributed to you, and you owe tax on it even if you reinvest the distribution and never sell a share yourself.
ETFs reduce that problem through in kind redemptions. When a large institution wants to cash out, the ETF delivers the underlying securities instead of selling them. That transfer doesn’t trigger a taxable event inside the fund, so fewer capital gains flow to remaining shareholders. The mechanism works only for very large redemptions (creation and redemption units worth millions of dollars), but all ETF investors benefit from the structural advantage.
Active mutual funds don’t have that escape hatch. Higher turnover plus traditional cash redemptions mean more frequent and larger capital gains distributions. In a taxable account, that can cut your after tax return by one to two percentage points annually compared to a low turnover index fund or ETF.
Four tax and placement takeaways:
- Index funds and ETFs fit well in taxable accounts because low turnover and in kind redemptions minimize taxable distributions.
- Active funds usually make more sense inside IRAs, 401(k)s, or other tax advantaged accounts where gains and distributions don’t trigger immediate tax bills.
- Tax loss harvesting works best with individual securities or direct indexing, not traditional mutual funds, because you control exactly when to sell.
- Holding period matters. Funds you plan to own for decades benefit most from tax efficient structures. Short term holdings face less tax drag because the compounding window is shorter.
If your core allocation sits in a taxable account, favor index funds and ETFs. If you’re building your core inside a 401(k) or IRA, the tax efficiency gap shrinks, and you can weigh active funds more on performance and fees alone.
Risk, Volatility, and Manager Dependence: Evaluating Each Approach for Core Stability
Index funds deliver predictable market beta. If the S&P 500 drops 15%, your S&P 500 index fund drops roughly 15%. Tracking error (how much the fund’s return diverges from the index) tends to stay under 0.10% to 0.30% annually for broad market funds. You know what you’re getting. The market’s return, minus a small fee, with very little surprise.
Active funds introduce performance dispersion. One large cap manager might beat the benchmark by 3% while another trails by 5% in the same year. That variability comes from concentrated bets, sector tilts, and manager judgment calls. When those calls work, you outperform. When they don’t, you lag, and you still pay the higher fee. Manager turnover adds another layer of risk. If the lead portfolio manager leaves, the fund’s strategy and results can shift abruptly.
Four risk considerations for core allocations:
- Tracking error. Index funds keep it minimal. Active funds accept wide dispersion as the price of potential outperformance.
- Downside protection. Some active managers try to limit drawdowns in bear markets, but success is inconsistent and hard to predict.
- Concentration risk. Active funds often hold 30 to 80 positions instead of 500 or more. A few bad stock picks can drag performance.
- Manager risk. Index funds eliminate it entirely. Active funds depend on the skill, discipline, and tenure of the portfolio management team.
When evaluating active funds for a core role, check the Sharpe Ratio (return per unit of risk) and compare maximum drawdowns during past bear markets. If an active fund charges 1.00% and delivers similar or worse risk adjusted returns than a 0.10% index fund, the higher fee isn’t justified. For core stability, favor funds with long track records, low manager turnover, and demonstrated ability to limit losses without sacrificing long term returns.
Allocation Guidance: How to Combine Index and Active Funds for a Balanced Core
A balanced core blends the cost control and consistency of index funds with selective active exposure where conviction and evidence justify higher fees. Common frameworks allocate 70% to 90% to low cost index funds and 10% to 30% to active “satellite” positions. The index portion delivers broad diversification and predictable market returns. The active slice targets outperformance in specific niches or themes.
Sample Allocation Models
A conservative starting split is 80% index and 20% active. The index piece might be a total U.S. stock market fund, a total international fund, and a core bond index, each weighted by your risk tolerance and time horizon. The active 20% could include a small cap manager with a long track record, an emerging markets fund where information inefficiencies favor skilled research, or a tax managed municipal bond fund in a taxable account.
Higher active allocations (30% to 40%) make sense only if you have strong conviction in specific managers, access to low fee institutional share classes, or exposure to markets where active management has shown persistent advantage. Beyond 40% active, you’re betting heavily on manager skill and accepting materially higher fees and tax drag across the portfolio.
| Model Type | Index % | Active % | Use Case |
|---|---|---|---|
| Passive core | 90–100% | 0–10% | Maximum simplicity, lowest cost, minimal monitoring; ideal for hands off long term growth |
| Conservative blend | 80% | 20% | Index for broad exposure; small active satellite for targeted conviction areas |
| Moderate blend | 70% | 30% | Balanced approach; active in small cap, emerging markets, or specialty fixed income |
| Active leaning core | 60% | 40% | High conviction in multiple active managers; requires close monitoring and higher risk tolerance |
| Fully active | 0–10% | 90–100% | Rare; suitable only for investors with manager access, deep research capacity, and strong conviction |
Rebalance your core annually or when any allocation drifts more than 5 percentage points from target. If your 80/20 index/active split becomes 75/25 after a strong year for active managers, trim the active sleeve and top up the index funds. Review active managers every three to five years. Check performance persistence, manager tenure, strategy drift, and fee levels. If a fund trails its benchmark for two consecutive multi year periods or key managers leave, consider replacing it with another active option or shifting that allocation to index funds. Adjust your active share upward only when you have clear evidence (specific manager skill, niche market inefficiency, or tax managed strategy advantages) that justify the higher cost and monitoring load.
Final Words
We compared long-term fit, fee drag, tax and turnover, historical evidence, and allocation guidance for core portfolios.
Bottom line: index funds usually win for a core because they’re low-cost, broadly diversified, and tax friendly. Active funds can add value in niche areas, but they bring higher fees, more turnover, and more monitoring.
So anchor most of your core with low-cost passive funds and keep a small, well-justified active sleeve. index funds vs active funds for core portfolio, either approach can work if you stick to the rules and stay steady.
FAQ
Q: What is a core portfolio and how do index and active funds fit into it?
A: The core portfolio is the long-term sleeve (usually 60–90% of assets) meant for steady market exposure; index funds give broad, low-cost diversification while active funds add selective, higher‑maintenance conviction bets.
Q: Which is better as a long-term anchor: index funds or active funds?
A: Index funds are usually better as long-term anchors because they cost less, provide predictable market returns, and avoid manager risk; active funds can help in small, well-researched parts of the core.
Q: How do index funds work and why are they suitable for core holdings?
A: Index funds replicate a benchmark fully or by sampling, keeping low turnover and small tracking error; that combination gives steady, low-cost exposure ideal for a core allocation.
Q: When should I include active funds in my core allocation?
A: You should include active funds in core when markets are inefficient, you trust a skilled, stable manager, or need niche fixed-income exposure; keep active allocations limited and monitored.
Q: How do expense ratios and fees affect long-term returns?
A: Expense ratios and fees reduce long-term returns through compounding; for example, $100k with a 0.08% fee can grow to about $746k versus about $609k with a 0.80% fee over 30 years.
Q: How should I place index and active funds between taxable and retirement accounts?
A: You should place high-turnover active funds inside tax-advantaged accounts; index ETFs and low-turnover funds suit taxable accounts because ETF in-kind redemptions limit capital gains.
Q: What does the historical evidence say about active managers versus index funds?
A: The historical evidence is mixed: in a 10-year sample ending March 31, 2026, about 79% of active stock and 83% of active bond funds outperformed, though longer studies often show many active funds underperform after fees.
Q: What are the main risks of using active funds in a core portfolio?
A: The main risks with active funds are manager dependence, higher turnover and tax drag, performance inconsistency, and concentration risk, all of which demand active monitoring and exit rules.
Q: How should I combine index and active funds in a balanced core?
A: Combine by anchoring 70%–90% in index funds and 10%–30% in active satellites, rebalance annually or after a 5-point drift, and size active bets to conviction and risk tolerance.
Q: How do I evaluate an active manager for a core allocation?
A: You should evaluate an active manager by checking tenure, consistent after‑fee returns, Sharpe ratio, capacity limits, downside record, and whether their process looks repeatable across market cycles.