
Think R-squared proves a fund manager’s skill? It doesn’t.
R-squared simply measures how much of a fund’s ups and downs line up with a chosen benchmark.
A high R² means the benchmark explains most moves. A low R² means the fund is doing something different or the benchmark is wrong.
This number is useful, but only when you use it the right way.
Thesis: Learn how to read R-squared, spot benchmark mismatch or closet indexing, and combine it with beta, alpha, and active share before you judge a fund.
Core Meaning of R‑Squared When Analyzing Fund Performance
R-squared (R²) measures how much of a fund’s return variance gets explained by the benchmark index’s return variance. You’ll see it as a percentage from 0 to 100%, or sometimes as a decimal from 0.00 to 1.00. When a fund shows R² of 95%, it means 95% of the fund’s ups and downs trace back to the benchmark’s ups and downs. The leftover 5% comes from somewhere else: manager decisions, sector bets, individual stock picks, or just noise.
This comes straight from regression analysis. You’re taking the fund’s returns at each point in time and modeling them as a function of the benchmark’s returns at that same moment.
The relationship looks like this: Fundreturn at time t = α (alpha) + β (beta) × Benchmarkreturn at time t + ε (error). In this setup, R² equals 1 minus the ratio of unexplained variance to total variance (R² = 1 − SSE/SST, where SSE is the sum of squared residuals and SST is the total sum of squares). A fund that moves almost identically to its benchmark ends up with very high R². Most of its return movements just follow the benchmark. A fund with lots of unique holdings or a different approach ends up with lower R², because much of its return pattern runs independent of the benchmark.
Here’s what matters: R-squared tells you what is driving returns, not how good those returns are. It doesn’t measure skill, risk-adjusted performance, or whether you should buy the fund. Just explanatory power.
What R² measures: The proportion of a fund’s return variance explained by a benchmark’s return variance.
What R² doesn’t measure: Fund quality, manager skill, risk-adjusted returns, or whether the fund belongs in your portfolio.
The regression relationship: The fund’s returns get regressed on the benchmark’s returns to produce alpha (intercept), beta (slope), and R² (goodness of fit).
Simple numeric example: An index fund tracking the S&P 500 might show R² = 0.95 (95%). That means 95% of its monthly return variation comes from the S&P 500’s monthly return variation.
How R‑Squared Is Calculated in Fund Analysis
Calculating R-squared for a fund requires two matched time series of returns, one for the fund and one for the benchmark, over the same period. Most analysts use monthly returns, though daily returns work for short-term or high-frequency analysis. Standard reporting windows are 36 months (three years) or 60 months (five years). These periods give you enough data points to produce stable regression estimates without washing out recent behavior. Once you’ve got the data, R² can be computed two ways: run an ordinary least squares (OLS) regression and pull out the R² statistic, or compute the correlation between fund and benchmark returns and square it (R² = correlation²).
The correlation method uses this formula: correlation = covariance(fund, benchmark) / (SDfund × SDbenchmark), where SD stands for standard deviation. After you calculate correlation, squaring it gives R². If the correlation is 0.9487, then R² = 0.9487² ≈ 0.90 or 90%. The regression method gives you extra outputs: alpha, beta, and statistical significance tests. Most professional tools and fund fact sheets report R² from regression.
Here’s the step-by-step:
- Gather matched return data for the fund and benchmark over your chosen time window (e.g., 36 monthly observations).
- Compute the covariance of fund and benchmark returns.
- Compute the standard deviations of both return series.
- Calculate the correlation using the formula above, or run the OLS regression directly.
- Square the correlation (or read R² from the regression output) to get the coefficient of determination.
Worked example: Suppose total variance (SST) of fund returns is 120, and unexplained variance (SSE) from the regression is 12. Then R² = 1 − 12/120 = 1 − 0.10 = 0.90, or 90%.
Practical Interpretation of R‑Squared for Mutual Funds and ETFs
Once you’ve got an R² number, you need to know what it actually means. The key insight is that R-squared shows how tightly a fund’s behavior links to the benchmark’s behavior, not how well the fund performs. High R² means the benchmark is a good predictor of the fund’s returns. Low R² means the fund is doing something different, either intentionally through active management, or because the benchmark doesn’t fit the fund’s strategy.
The industry uses rough thresholds to classify funds. An R² of 90% or above (0.90 or higher) indicates the fund’s returns are largely explained by the benchmark. You’d expect this for index funds, ETFs that track a major index, or highly systematic passive strategies. An R² between 70% and 90% suggests strong but not perfect benchmark alignment. The fund might have sector tilts, a value or growth bias, or modest stock selection that adds some independent movement. An R² below 70% signals low explanatory power from the chosen benchmark. This can mean the fund is truly active, pursues a concentrated or alternative strategy, or the benchmark simply doesn’t match the fund’s actual investment universe.
| R-Squared Range | Interpretation |
|---|---|
| ≥ 90% | Tight benchmark relationship; fund behaves like the index; beta and tracking error are reliable; expect index-like exposure. |
| 70–90% | Moderate benchmark dependence; fund has meaningful benchmark exposure but also independent drivers from style, sector, or stock selection. |
| < 70% | Low explanatory power; fund returns driven by factors outside the benchmark; verify benchmark fit or evaluate on strategy-specific metrics. |
Understanding these ranges helps you set expectations. If you’re buying what you think is an S&P 500 index fund and see R² = 98%, that’s confirmation. If you’re evaluating an “active growth” fund with R² = 95%, you might ask why it’s charging active fees when it’s basically hugging the index. That’s sometimes called closet indexing.
How R‑Squared Relates to Beta, Alpha, Tracking Error, and Manager Skill
R-squared doesn’t work in isolation. It teams up with beta, alpha, tracking error, and active share to paint a complete picture of how a fund operates. Beta measures how sensitive the fund is to benchmark movements. A beta of 1.0 means the fund moves in lockstep with the benchmark; beta above 1.0 means amplified swings; beta below 1.0 means dampened moves. But beta only makes sense when R² is reasonably high. If R² is low (say, 30%), then the benchmark explains so little of the fund’s behavior that the beta number becomes unreliable and potentially misleading.
Alpha is the return left over after accounting for beta. It’s the manager’s added value (or subtracted cost) relative to the benchmark. A fund with high R² and positive alpha is delivering benchmark exposure plus a consistent extra return. A fund with low R² and positive alpha might be outperforming, but you can’t be sure the alpha is real skill versus benchmark mismatch. The chosen benchmark might simply be the wrong measuring stick. Tracking error (the standard deviation of active returns, fund return minus benchmark return) usually moves inversely to R². High R² typically means low tracking error, because the fund sticks close to the benchmark. Low R² usually means higher tracking error, because the fund’s returns diverge.
Combining R² with active share (the percentage of fund holdings that differ from the benchmark) helps spot closet indexers. A fund with R² ≥ 90% and active share ≤ 60% is likely charging active fees while delivering near-index returns. Red flag for cost-conscious investors.
High R² makes beta and alpha estimates more reliable because the benchmark truly explains most of the fund’s movements.
Low R² undermines benchmark-relative metrics; beta and alpha may reflect benchmark mismatch more than manager decisions.
Tracking error and R² usually move inversely; tight tracking (low TE) pairs with high R², and wide tracking (high TE) pairs with low R².
Active share plus R² reveals closet indexing; R² ≥ 90% with active share ≤ 60% suggests the fund isn’t genuinely active despite what the marketing says.
Benchmark Selection Effects on R‑Squared Reliability
The R² number you see is only as good as the benchmark you chose. Pick the wrong benchmark, and R² becomes meaningless. Or worse, misleading. A global equity fund measured against the S&P 500 will show artificially low R², not because the manager is skilled or independent, but because the S&P 500 is a U.S. large-cap index and the fund holds international stocks. The correct benchmark for that fund might be the MSCI World or MSCI ACWI. Switch to the right benchmark, and R² might jump from 30% to 85%, completely changing the interpretation.
Benchmark selection should match the fund’s stated strategy, investment universe, capitalization range, sector focus, and geographic footprint. A small-cap value fund should be benchmarked to a small-cap value index, not the S&P 500. A sector-specialist technology fund should use a technology index. When a fund’s R² is surprisingly low, the first question isn’t “Is the manager doing something unique?” but “Did I choose the right benchmark?” Rolling-window R² analysis (computing R² over successive 36-month windows and plotting the results over time) can reveal style drift. A fund that had R² = 92% from 2018 to 2021 but drops to R² = 55% from 2022 to 2024 may have shifted strategy, changed managers, or responded to market regime changes.
Common benchmark selection mistakes include:
Using a broad market index (e.g., S&P 500) for a style-specific or sector fund.
Choosing a domestic benchmark for a global or international fund.
Ignoring capitalization mismatches (large-cap benchmark for a mid-cap fund).
Using Rolling R‑Squared and Time-Window Selection to Understand Strategy Behavior
A single R² number is a snapshot. It tells you how well the benchmark explained the fund’s returns over one fixed period, but it doesn’t show whether that relationship is stable or changing. Rolling R-squared analysis solves this by computing R² over a moving window (typically 36 months) and shifting the window forward one month at a time. The result is a time series of R² values that reveals how the fund’s benchmark correlation has evolved. A fund that shows steady R² around 85% for years, then suddenly drops to 50%, may have changed portfolio managers, shifted from large-cap to mid-cap, or adopted a more concentrated strategy.
The choice of time window matters. One-year windows (12 monthly returns) are short and noisy; they capture recent behavior but produce unstable estimates. Three-year windows (36 months) are the industry standard. Long enough to smooth out short-term volatility, short enough to detect meaningful changes. Five-year windows (60 months) are very stable but can mask recent strategy shifts. Daily returns instead of monthly returns can be used for high-frequency or short-duration analysis, but daily data introduces more noise and requires larger sample sizes to be reliable.
To compute rolling R²:
- Select your window length (e.g., 36 months).
- Run a regression of fund returns on benchmark returns for the first 36-month period.
- Record the R² value and the end date of that window.
- Shift the window forward by one month, drop the oldest month, add the newest month, and run the regression again.
- Repeat the process through the entire data series, then plot R² values over time to see trends and breaks.
Adjusted R‑Squared and Multi-Factor Analysis for Funds
Standard R² always increases (or stays the same) when you add more independent variables to a regression, even if those variables add no real explanatory power. Adjusted R² corrects for this by penalizing the addition of extra factors, making it a more honest measure when comparing models with different numbers of inputs. In single-benchmark fund analysis, adjusted R² and regular R² are nearly identical. The difference becomes meaningful when you move to multi-factor models: regressions that include size, value, momentum, or quality factors alongside the market benchmark.
The Fama-French three-factor model adds a size factor (small-cap minus large-cap) and a value factor (high book-to-market minus low book-to-market) to the market return. The Carhart four-factor model adds a momentum factor. These multi-factor regressions often produce higher adjusted R² than a single-benchmark regression, because they capture systematic tilts that a broad market index misses. A fund with R² = 75% against the S&P 500 might show adjusted R² = 88% in a four-factor model, revealing that much of the “unexplained” variance was actually exposure to size, value, or momentum. The alpha estimate also changes. What looked like manager skill in the single-factor model may turn out to be factor exposure that wasn’t priced into the benchmark.
Using adjusted R² and multi-factor analysis improves the reliability of beta and alpha estimates, especially for funds that tilt toward specific styles or factors. It makes sure you’re not mistaking systematic factor exposure for active stock-picking skill.
Limitations and Pitfalls When R‑Squared Is Misinterpreted
R-squared is a powerful diagnostic, but it’s easy to misuse. The most common mistake is treating high R² as proof of quality or low R² as proof of skill. R² only measures how well the benchmark explains returns; it says nothing about whether those returns are good. A fund can have R² = 98% and still deliver terrible performance if it tracks a declining benchmark or charges high fees. A fund can have R² = 40% and add no value if the 60% unexplained variance is just random noise or poor stock picks.
R² is also highly sensitive to the time period, return frequency, and presence of outliers. A single extreme month (a big gain or loss that doesn’t match the benchmark) can pull R² down sharply in a short sample. Small sample sizes (fewer than 24 monthly observations) produce unstable R² estimates that jump around with each new data point. Funds that use options, hedging, or leverage can show low R² even when the benchmark is conceptually correct, because the return pattern is nonlinear. And using the wrong benchmark (covered earlier) distorts R² in ways that have nothing to do with manager behavior.
Key pitfalls to watch for:
Benchmark mismatch: Low R² may reflect a bad benchmark choice, not genuine active management.
Small sample size: Fewer than 24–36 months of data produces unreliable R² estimates.
Nonlinear strategies: Funds using options, hedging, or leverage can show artificially low R² despite tracking a conceptually appropriate benchmark.
Outliers: A few extreme return months can distort R² in either direction.
False skill signals: High alpha with low R² might mean the benchmark is wrong, not that the manager is skilled; verify benchmark fit before celebrating alpha.
Practical Investor Applications of R‑Squared in Fund Selection
Knowing how to calculate and interpret R² is useful. Knowing what to do with it is essential. R-squared becomes a screening and due-diligence tool when you combine it with clear decision rules. If you want low-cost index exposure, you should look for funds with R² ≥ 90% relative to your target benchmark, then compare expense ratios and tracking error to find the cheapest, tightest tracker. If you’re hiring an active manager, you want R² in a range that reflects genuine active decisions (typically 40% to 85%), and you want to see that the deviations from the benchmark (captured in alpha and tracking error) have been rewarded with higher risk-adjusted returns net of fees.
Combining R² with active share helps detect benchmark-hugging funds that charge active fees but deliver passive exposure. A fund with R² = 92% and active share = 55% is doing very little that differs from the index, so you should pay index-fund fees, not active-fund fees. Rolling R² analysis helps spot style drift. If a fund’s three-year rolling R² drops from 88% to 60% over two years, the manager may have changed the portfolio’s character, and you should reassess whether it still fits your allocation.
Here’s a practical due-diligence checklist using R²:
- Compute R² over multiple windows (1-year, 3-year, 5-year) to see if the relationship is stable or changing.
- Compare R² to tracking error: high R² should pair with low TE; if R² is high but TE is also high, investigate concentrated bets or derivatives.
- Examine alpha alongside R²: if R² is low, check whether alpha is statistically significant and whether the benchmark is appropriate.
- Check the benchmark match: verify the benchmark reflects the fund’s actual style, cap range, sector focus, and geography.
- Evaluate active share and R² together: flag funds with R² ≥ 90% and active share ≤ 60% as potential closet indexers.
- Review rolling R² patterns: look for sudden changes that signal strategy drift, manager turnover, or portfolio restructuring.
Numerical Case Studies to Interpret R‑Squared Outputs
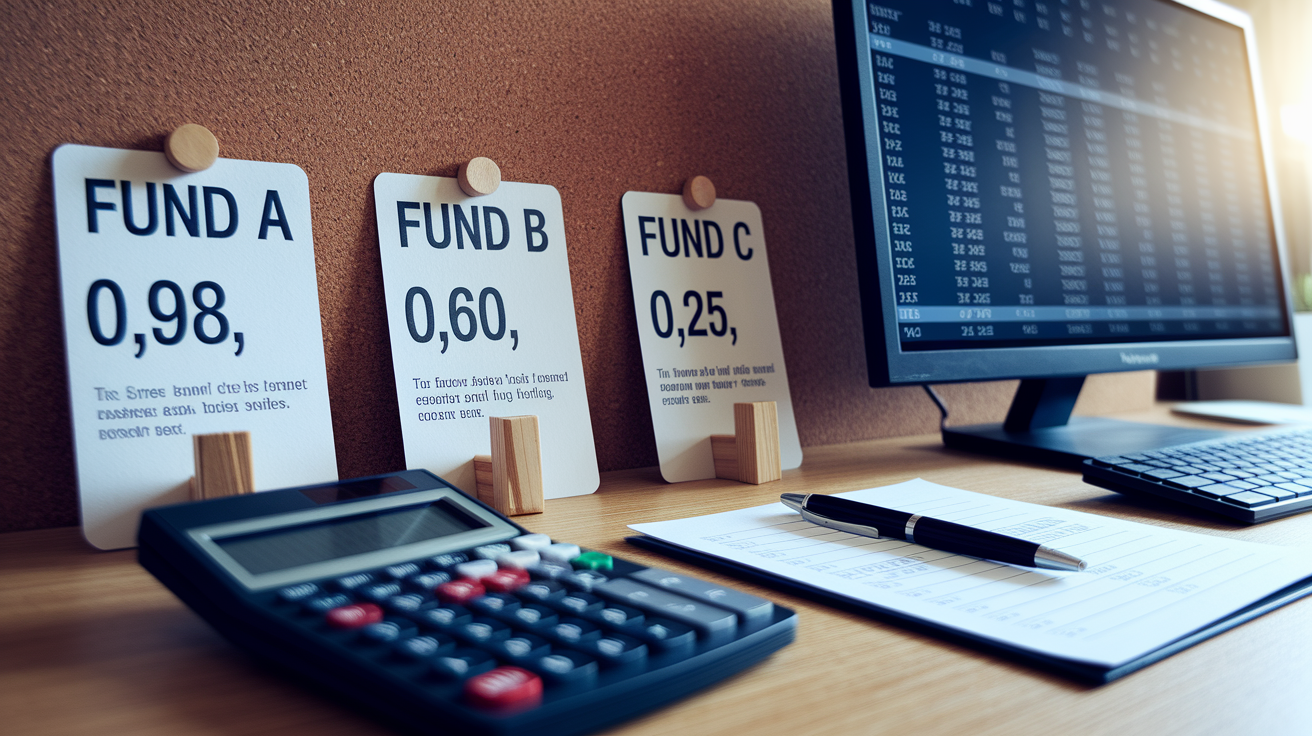
Concrete examples make the thresholds and relationships clear. Consider three hypothetical funds analyzed over a 36-month period using monthly returns. Fund A is a passive S&P 500 index ETF. The regression against the S&P 500 produces R² = 0.98 (98%), beta = 1.00, alpha = −0.10% annualized, and tracking error = 0.3% per year. The interpretation: the benchmark explains 98% of return variance, the fund moves exactly with the index (beta = 1), and the small negative alpha and tiny tracking error reflect the fund’s low expense ratio and minor cash drag. For an investor seeking pure S&P 500 exposure, this fund is doing exactly what it should.
Fund B is an actively managed large-cap growth mutual fund, also benchmarked to the S&P 500. The regression shows R² = 0.60 (60%), beta = 1.08, alpha = 0.35% annualized, and tracking error = 4.5%. The interpretation: 60% of return variance comes from the S&P 500, and 40% is independent. The beta slightly above 1 suggests the fund is a bit more volatile than the index, the positive alpha indicates the manager added value over the period, and the 4.5% tracking error confirms meaningful active positions. This fund is genuinely active, and you’d evaluate whether the alpha justifies the fee and whether 4.5% of extra volatility fits your risk tolerance.
Fund C is a global sector-specialist fund benchmarked (perhaps incorrectly) to the MSCI World. The regression produces R² = 0.25 (25%), beta = 0.50, alpha = 1.2% annualized, and tracking error = 9%. The interpretation: the MSCI World explains only 25% of variance, so this benchmark is a poor fit. The low beta and high alpha might look impressive, but they likely reflect benchmark mismatch rather than pure skill. Before concluding the manager is adding value, you’d test alternative benchmarks (a sector index, a regional index, or a multi-factor model) to see if explanatory power improves and alpha shrinks.
| Example Fund | R² Value | Interpretation |
|---|---|---|
| Fund A (S&P 500 Index ETF) | 0.98 (98%) | Near-perfect tracking; benchmark explains almost all variance; expect low fees and minimal tracking error. |
| Fund B (Active Large-Cap Growth) | 0.60 (60%) | Moderate benchmark dependence; meaningful active positions; evaluate alpha and tracking error to judge skill. |
| Fund C (Global Sector Specialist) | 0.25 (25%) | Low explanatory power; likely benchmark mismatch; test alternative benchmarks before assessing manager skill. |
Final Words
We defined r-squared, showed how to calculate it with regression and correlation, and ran through numeric examples to make the math feel real. We also explained how it connects to beta, alpha, tracking error, and why picking the right benchmark matters.
You saw rolling windows, adjusted R² for factor models, common pitfalls, and a short due-diligence checklist to apply.
Treat r-squared in fund performance analysis as a useful signal, not the whole story. Combine it with a few other checks, and you’ll make steadier, more confident fund choices.
FAQ
Q: What is a good R-squared for a fund?
A: A good R-squared for a fund depends on whether you want index-like tracking or active independence. Higher R² means closer benchmark tracking; lower R² suggests a more independent strategy or possible benchmark mismatch.
Q: What does an R2 of 0.5 mean? Is an R2 of 0.2 good?
A: An R2 of 0.5 means 50% of the fund’s return variance is explained by the benchmark. An R2 of 0.2 (20%) shows weak benchmark fit—fine for unconstrained active managers, not for funds meant to closely track an index.
Q: What is the r2 of a mutual fund?
A: The R-squared of a mutual fund is the percent of its return variance explained by its chosen benchmark. Index funds often show R² in the high 90s, while active or niche funds typically report much lower R².